Fix and Flipping in Chicago: What Real Estate Investors Should Know in 2026
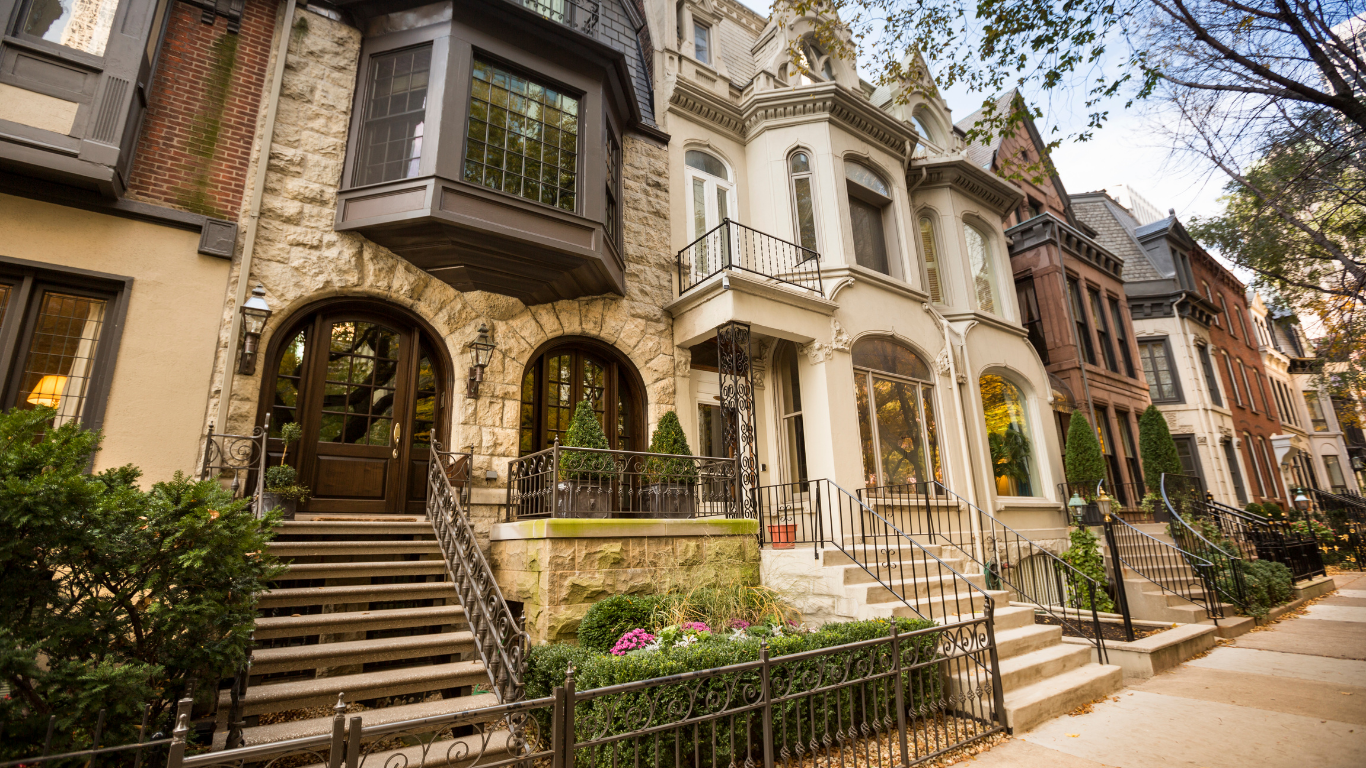
Chicago offers fix and flip investors something that many markets can’t: a large diverse housing market with a range of property types, price points, neighborhoods, and potential buyers.
But that variety also makes Chicago a market where investors need to know their numbers.
A renovation strategy that works in one neighborhood may not make sense in another. Property taxes, older housing stock, permitting requirements, renovation costs, financing expenses, and neighborhood-level buyer demand can all influence whether a Chicago fix and flip ultimately works.
For investors considering flipping a house in Chicago in 2026, understanding the local market is just as important as finding the property itself.
Here’s what to consider before taking on a Chicago fix and flip.
Is Chicago a Good Market for Fix and Flips in 2026?
Illinois continues to see meaningful fix and flip activity.
According to ATTOM’s Q1 2026 home-flipping data, 2,132 homes were flipping in Illinois during the first quarter of the year. Flips represented 7.1% of statewide home sales.
ATTOM reported a typical gross flipping profit of $81,500 in Illinois and a typical gross return on investment of 45.9%.
Those figures can provide useful context, but they don’t represent what every Illinois or Chicago investor actually earns.
Gross flipping returns measure the difference between acquisition and resale prices. They do not account for renovation costs and other expenses associated with completing a flip.
For an investor evaluating a Chicago property, the individual deal matters much more than a statewide average.
Chicago is Not One Real Estate Market
One of the most important things to understand about investing in Chicago is that there is no single “Chicago Housing market.”
The city contains dozens of neighborhoods with dramatically different:
Home prices
Property types
Buyer demographics
Renovation expectations
Property taxes
Inventory levels
Days on market
Resale values
The broader Chicago metropolitan area adds even more variation.
That’s why investors shouldn’t use a citywide median home price to determine whether a particular property makes sense.
A property’s potential should be evaluated against a relevant comparable properties in the same area, with similar characteristics and a similar target buyer.
Older Housing Stock Can Create Opportunity and Risk
Chicago’s older housing stock is part of what can make the market attractive to fix and flip investors.
Older homes can provide opportunities to modernize outdated properties, improve layouts, replace aging systems, and reposition homes for today’s buyers.
But older properties can also come with more expensive surprises.
Investors should place close attention to:
Electrical systems
Plumbing
Roof condition
Foundations
Sewer lines
HVAC
Windows
Water intrusion
Masonry
Structural issues
Previous renovations
Cosmetic problems are relatively easy to budget.
Before buying an older Chicago property, investors should understand which systems have already been updated and which may need to be addressed during the renovation.
Property Taxes Need to Be Part of the Deal Analysis
Property taxes are an important consideration for Chicago-area investors.
They can affect the project in two ways:
First, property taxes contribute to holding costs while the investor owns the property.
Second, taxes can affect affordability for the eventual buyer.
When comparing potential projects, investors should consider the complete monthly carrying cost rather than focusing only on loan payments and renovation expenses.
A project that takes several months longer than expected can mean additional taxes, interests, utilities, and maintenance.
Those costs reduce the amount left when the property eventually sells.
Chicago Renovation Costs Can Vary Significantly
The cost to renovate a Chicago property depends heavily on the scope of work.
A cosmetic flip involving paint, flooring, fixtures, and finishes is very different from a project involving major mechanical, structural, or layout changes.
Renovation costs can also vary based on:
Property age
Property type
Contractor availability
Material selection
Permitting requirements
Project complexity
Neighborhood
Condition of major systems
Investors shouldn’t assume the renovation cost from their latest project will apply to the next one.
Build the budget based on the actual property.
And leave room for contingency, particularly when renovating an older home.
Understand Chicago Permitting Before Construction Begins
Permitting can affect both the cost and timeline of a renovation.
Depending on the scope of work, certain projects may require permits, plan review, inspections, or licensed professionals.
That means investors should determine permitting requirements before finalizing the renovation schedule.
A project that appears achievable within four months may look different if significant structural, electrical, plumbing, or other permitted work is required.
Timeline matters because delays don’t affect the construction schedule.
They can also increase:
Loan interest
Insurance
Taxes
Utilities
Maintenance
Other holding expenses
When underwriting a Chicago fix and flip, build the expected permitting and inspection process into the timeline rather than treating it as an afterthought.
ARV Should Be Extremely Local
After Repair Value, or ARV, is one of the most important numbers in a fix and flip.
In Chicago, Investors should be particularly careful about which comparable sales they use.
A property, a few blocks away may be in a different school boundary, neighborhood pocket, property type, or buyer market.
Look for recently sold properties that are as similar as possible in:
Location
Property type
Square footage
Bedroom and bathroom count
Lot size
Condition
Renovation quality
Parking
Basement configuration
Other features buyers value
The goal isn’t to find the highest-priced renovated home nearby.
It’s to determine what the subject property could realistically sell for after the planned renovation.
Know Your Chicago Property Types
Chicago gives investors a range of residential property types to consider.
Depending on the location, investors may encounter:
Single-family homes
Bungalows
Brick homes
Row homes
Condominiums
Townhomes
Two-flats
Three-flats
Small multifamily properties
Each can require a different investment strategy.
The buyer for a renovated single-family home may have very different expectations from someone purchasing a condo or small multifamily property.
Property type can also affect renovation scope, financing, association requirements, taxes, and exit strategy.
Investors should understand the property they’re buying, not simply the neighborhood it’s located in.
What Chicago Buyers Expected
The renovation should reflect the property’s likely buyer and price point.
That doesn’t necessarily necessarily mean using the most expensive finishes.
In fact, over-improving a property can reduce profitability if comparable sales don’t support the additional spending.
Before determining the scope of work, look at recently renovated homes that are sold successfully.
Pay attention to:
Kitchen finishes
Bathroom finishes
Flooring
Lighting
Layout
Storage
Appliances
Exterior condition
Outdoor space
Parking
Then compare those properties with homes currently listed for sale.
Sold properties show what buyers have paid for.
Active listings show what your finished property may eventually compete against.
Parking Can Matter More Than Investors Expect
In a dense city, parking can be an important part of a property’s appeal.
A garage, dedicated parking space, or lack of parking may influence buyer demand depending on the neighborhood and property type.
Investors shouldn’t assume interior renovation alone determines resale value.
The complete property matters.
When evaluating comparable sales, make sure you’re comparing properties with similar parking situations whenever possible.
Don’t Ignore the Basement
Basements are common in many Chicago properties and deserve careful attention during due diligence.
Investors should look for signs of:
Water intrusion
Foundation issues
Drainage problems
Mold
Low ceiling height
Improper previous renovations
A finished basement may add functionality and buyer appeal, but investors should avoid automatically assigning the same value to below-grade space as above-grade living space.
Use relevant local comparable sales to determine how buyers in that specific market value the additional space.
Your Renovation Timeline Affects Your Profit
Time matters in every fix and flip.
ATTOM reported that the typical U.S. home flipped in Q1 2026 took 165 days from purchase to resale.
Your Chicago project may be shorter or longer depending on the property, scope, permits, contractors, listing period, and buyer.
That’s why it’s helpful to build more than one timeline into your underwriting.
Consider:
Best case: Construction and sale proceed according to plan
Expected case: Normal delays occur
Stress case: Construction or the eventual sale takes significantly longer.
Then calculate what happens to your projected profit under each scenario.
Financing Should Be Considered Before You Make an Offer
Investors should understand their financing options before they’re under contract.
A fix and flip loan may need to account for bother acquisition and renovation costs, depending on the structure.
Before making an offer, understand:
How much capital you may need at closing
How renovation funds are structured
How draws work
What liquidity may be required
Loan costs
Loan term
Expected closing timeline
This is particularly important when competing for a property where the seller expects a quick or reliable closing.
Knowing your financing structure ahead of time makes it easier to determine what you can realistically offer.
Don’t Underestimate Holding Costs
Holding costs can quietly reduce the profitability of a Chicago flip.
Depending on the project, investors may need to account for:
Loan interest
Property taxes
Insurance
Utilities
Snow removal
Landscaping
Security
HOA expenses
Maintenance
A delay of one month may not sound significant.
But several additional months, can materially change the final return.
When analyzing the deal, calculate holding costs using a realistic timeline rather than assuming everything will go perfectly.
Distressed Properties May Create Acquisition Opportunities
Distressed and lender-owned properties can be another source of potential fix and flip opportunities.
ATTOM reported that lender-owned properties accounted for 4.4% of Chicago-area home sales in Q1 2026, placing Chicago among the Metropolitan areas with the highest shares of lender-owned sales during the quarter.
That doesn’t mean every distressed property is a good investment.
These properties may require substantial repairs or come with additional due-diligence considerations.
Investors still need to evaluate the property based on:
Purchase price
Condition
Renovation cost
Title
ARV
Financing
Holding period
Exit strategy
A discounted purchase price only matters if the complete deal works.
How to Evaluate a Chicago Fix and Flip Deal
Before purchasing a property, build out the entire project.
Start with:
Purchase price
What will it actually cost to acquire the property?
Renovation budget
What work is required to create a competitive finished product?
Contingency
What happens if unexpected repairs appear?
ARV
What do relevant renovated comparable properties support?
Financing costs
How much will the capital cost over the expected project timeline?
Holding costs
Include taxes, insurance, utilities, maintenance, and other expenses.
Selling costs
Account for the expenses associated with eventually selling the property.
Timeline
How long will renovation, listing, and closing realistically take?
Once those numbers are established, stress-test them.
When happens if the renovation costs 10% more?
What happens if the property sells for less than projected?
What happens if the project takes two months longer?
If a small change eliminates the expected profit, the deal may not have enough margin for error.
Common Mistakes When Flipping a House in Chicago
Chicago’s size and variety can create opportunities, but they can also make assumptions dangerous.
Common mistakes include:
Using the wrong comps.
A nearby property isn’t necessarily comparable.
Underestimating an older home’s renovation needs.
Cosmetic updates may reveal larger mechanical or structural problems.
Ignoring property taxes.
Taxes affect both holding costs and buyer affordability.
Over-improving the property.
Renovations should match the neighborhood price point.
Underestimating permits and timelines
Delays can increase the total project cost.
Assuming appreciation will save the deal.
The numbers should work based on supportable ARV, not hoped for future price growth.
Failing to plan the exit before buying.
Know who is likely to purchase the finished property and why.
Is Fix and Flipping in Chicago worth it?
Chicago can offer opportunities for fix and flip investors in 2026, but the city’s diversity makes disciplined underwriting especially important.
Illinois recorded a 45.9% typical gross flipping ROI in Q1 2026, but that number should be viewed as market context, not an expected investor return.
ATTOM’s methodology doesn’t subtract renovation costs and other project expenses from its gross-return calculation.
The profitability of an individual Chicago flip will depend on the purchase price, property condition, renovation budget, financing, holding period, resale value, and execution.
A good Chicago fix and flip isn’t simply an inexpensive property in a popular neighborhood.
It’s a property where the complete numbers make sense.
The Bottom Line
Fix and Flipping in Chicago in 2026 requires a local approach.
The city’s wide range of neighborhoods, property types, price points, taxes, renovation needs, and buyer expectations means investors should evaluate property by property.
Before purchasing a Chicago fix and flip, understand the property’s realistic ARV, renovation scope, permitting needs, financing structure, holding costs, and likely buyer.
Most importantly, leave room for the unexpected.
A conservative deal with realistic assumptions is better positioned to handle the surprises that can come with renovating an older Chicago property.